From hiring the right people and adapting processes to navigating acquisitions and investment, leaders from some of Manchester’s scaling success stories, including UrbanChain, Ryft, Moneyappi, Autotrader and Sustainable Smart Technologies, shared what changes as a business grows and the lessons they’ve learned along the way.
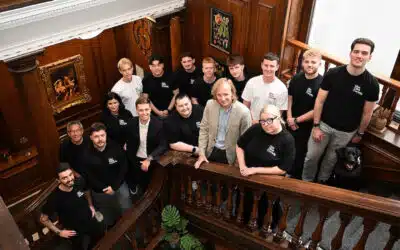
Just a stone’s throw from the new No 10 North base at Manchester’s Albert Square, it was a fitting location as founders, investors and industry leaders came together at Bruntwood SciTech’s Union building on 17 September to tackle why some promising tech businesses in the region break through while others stall.
It marked the first breakfast event in Prolific North’s continuing GRAFT Regional Tech Champions series, supported by MHA, GM Business Growth Hub and Vista Insurance.
Across two panel sessions, tech leaders first unpacked what actually changes inside a business as it scales, before industry leaders turned to what happens after investment lands and whether Greater Manchester has the right support in place to produce its next generation of tech champions.
What changes when a business starts to scale?
Lee Stretton, CTO at UrbanChain; Niamh Allen, managing director at Sustainable Smart Technologies; Peter Appleby, head of data science and analytics at Autotrader; and Callum Bentley-Edwards, head of growth at Ryft, kicked things off by getting into what really changes when growth accelerates, from overhauling systems and growing teams to expanding internationally.
For Stretton, who joined fast-growing cleantech firm UrbanChain after more than two decades working in financial services, one of the biggest challenges has been balancing “rapid industry change” with the company’s ambitions.
He recalled that when he joined UrbanChain two years ago, the business, having spun out of university research, still worked from spreadsheets. As the team and customer base grew, building stronger data infrastructure and automating processes became increasingly important.
Quizzed by Prolific North’s managing director, Alexandra Balazs, about UrbanChain’s unicorn ambitions, Stretton said the company continues to accelerate with impressive monthly growth but admitted it still has “a bit of time to go yet” before reaching that $1bn valuation.
Over at Sustainable Smart Technologies, previously known as IoT Horizon, the growth story has looked very different.
What started as a family-run business set up by Niamh Allen’s parents was soon a growing success story, with the business being snapped up by Sustainable Investments Ltd in 2024. Allen’s team went from nine people to becoming part of a 178-strong group almost overnight.

That “huge change” meant quickly adapting to new systems and processes, while developing a platform capable of scaling into thousands more homes.
Allen also revealed another lesson from the company’s early days. As a small software team back then, IoT Horizon was building different solutions for different clients across multiple sectors. The problem was that very little of it was repeatable.
The shift towards “repeatable products” became essential, particularly after shifting focus to housing, with the business rebuilding its platform and IP around technology that could be deployed again and again. “There’s a huge journey ahead of us now,” she said.
For Peter Appleby, who has spent around 12 years at Autotrader, growth has brought different challenges around people, culture and data.
He has helped grow his own team from one person to around 40 and said culture can be “very tight” when teams are small. As more people arrive, that inevitably begins to change. “You’ve got to be aware that the culture will shift,” he explained.
He shared the importance of searching in “more unusual places” for people with potential, which has helped in recruiting and finding “more people, more quickly” as the team has grown.
But he also believes businesses should think about data much earlier on. Small teams can make decisions quickly, which makes it tempting not to worry too much about the infrastructure sitting behind those decisions. Once a company grows, going back to fix it becomes considerably harder. His advice was simple: “Get your data house in order.”
Stretton agreed on the importance of getting the basics right early on too to prepare for rapid expansion, whether it be internal infrastructure or the team. When he first joined the business, he was employee number 30. Within three or four weeks, they hired dozens more. Now the business is up to around 85 staff, meaning it has become even more crucial to have the “right people, the right process and the right decisions” in place.
For growing businesses like Ryft, scaling increasingly means looking beyond the UK. The Manchester fintech announced a £20m Series B raise on the same day as the event, with Bentley-Edwards explaining how an “attitude shift” around 18 months ago moved the company beyond its historically UK-centric focus towards Europe and the US.
READ MORE: Manchester fintech Ryft lands £20m for European and US expansion
“You can’t just be a payments company specifically in one country if you want more investment, if you want more turnover and want to grow,” he said.
Ryft has now submitted an application for a full European Union payments licence, but that international ambition brings its own regulatory, recruitment and operational challenges.
It has also made the company’s “partner ecosystem” increasingly important in that scaling phase. Bentley-Edwards said businesses pursuing “aggressive growth” need to be selective about those relationships and consider what value they could bring further down the line. “Cut the chaff and keep focused,” he said.

But processes and systems are only part of the scale-up challenge. An audience question turned the discussion to whether a founder who builds a successful start-up can also make a great scale-up CEO.
Bentley-Edwards pointed to Ryft’s co-founder and CEO Sadra Hosseini, describing him as the company’s “North star”, who has previously exited several businesses. Crucially, Hosseini has surrounded himself with “experienced people and trusts them to deliver” on the company’s vision.
What happens when the investment lands?
Ray Law, founder of Moneyappi; Joe Ball, senior investment associate at PXN Group; Ian Dixon, digital, creative and tech sector growth specialist at GM Business Growth Hub; Dan Blake, director of private equity and M&A at Vista Insurance; and Rob Richardson, corporate finance partner at MHA then turned to what changes when investment lands, from the mistakes founders make in those crucial first months to the decisions that can come back to haunt them years later.

The first question quizzed the panel on what founders tend to get wrong in those crucial first 90 days when investment lands.
For Joe Ball, who shared how PXN Group is “doubling down” on investment following the recently announced £80m top-up for its NPIF II fund, one mistake he sees founders make is “rushing out to hire salespeople” when founders “should lead sales a lot longer” as they know the product best.
Noting a “slowdown” in deals over the past 12 months, Dan Blake from Vista Insurance said he had worked on around 400 investment deals during his 12 years at the firm. One of the biggest mistakes he had seen was businesses failing to get their risk infrastructure in place early enough, leaving them unprepared for that next stage of growth.
At MHA, Rob Richardson shared how he works with businesses ranging from start-ups to listed companies and sees another common misconception when capital arrives: founders seeing it as “job done”. Investment is “only just the beginning”, he said, with founders needing to think about what’s next.
But what about the founder perspective? Now building Manchester-based financial wellbeing platform Moneyappi, Ray Law is a second-time founder after exiting his previous business after 10 years.
READ MORE: Where Greater Manchester’s tech growth is happening — and what’s driving it
He explained there is a “big dynamic shift” when funding lands. A founder goes from selling the vision to suddenly being responsible for executing it, and even with a detailed plan for deploying the capital, that shift can lead to “paralysis” over what to tackle first.
“No matter how much you plan, and you can have the plan for capital deployment and exactly how you’re going to do it, but the narrative changes significantly. You’re going from storytelling to sell the vision to then actually having that capital and now you’ve got to execute that vision.”
For him, the solution is to build a good support network and a team to help build and execute on that vision.
From the investor side, Ball from PXN Group said “transparency” becomes particularly important during the first few months when a founder raises investment.
Trying to hide problems such as churn can quickly damage investor relationships, while founders should resist viewing their board as just a place to report numbers. Instead, founders should view the board as a “real decision-making asset”.
Some early decisions can come back to cause problems years later, particularly when a business is approached by a buyer before it has prepared for a sale.
Rob Richardson at MHA explained that overlooked issues around cap tables, promised shares and tax can suddenly complicate a deal. He stressed the importance of getting those foundations right early, from making sure the right people are rewarded through the cap table to keeping data and information up to date, long before an exit is on the table.
Dan Blake from Vista Insurance made a similar point from a risk perspective. Getting those structures in place early gives owners and investors greater confidence that the business is ready for its next phase of growth.
There is no “secret sauce” to getting things right, Joe Ball from PXN Group added, but having the right expertise around the board and cap table becomes increasingly important as founders move away from trying to be a “jack of all trades” and learn to delegate.
Is there enough support once businesses start scaling?
The discussion then moved beyond individual businesses to Greater Manchester itself.
Ian Dixon from GM Business Growth Hub pointed to research that identified more than 90 accelerators and programmes supporting early-stage businesses across the region. But for companies at scale-up stage or with high-growth potential, there were only “two or three”.

It highlighted what he sees as a missing piece in the ecosystem: peer support from people who have already been through the same journey.
One response has been GM Business Growth Hub’s ASCEND programme, which brings scale-up founders together and is now recruiting for its fourth cohort. For Dixon, founders such as Ray Law from Moneyappi who have already built, grown and exited businesses can be particularly valuable to those going through the process for the first time.
Joe Ball from PXN Group believes there is a wider UK challenge too. Many tech businesses reaching Series B are increasingly looking towards the US for investment. He has no issue with companies raising overseas, but believes more needs to be done to help them expand internationally without losing their roots or headquarters here.
For him, that could mean building a stronger collective playbook around everything from hiring and tax to customers and international expansion.
“We need to help our scale-up businesses to remain headquartered here, and arm them with the knowledge and the know-how to go and expand overseas.”
Dan Blake similarly encouraged founders to make better use of advisors already operating across the ecosystem and the importance of ensuring those networks are better connected.
Rob Richardson from MHA pointed to another ingredient: attitudes towards risk. For Manchester to produce more high-growth businesses, he said the focus needs to remain on building the community and presence around them while taking a more positive approach to risk.
The panel ended with one final scenario, asking who a founder should call first if they woke up tomorrow to find £1m of investment in the bank.
For Ray Law at Moneyappi, he’d be ringing a trusted partner while Dan Blake at Vista Insurance and Rob Richardson from MHA similarly pointed towards trusted advisors and financial expertise.
Drawing on his own experience of setting up a business in the 1990s, Ian Dixon from GM Business Growth Hub said calling a mentor and someone who has experienced the highs and lows first-hand can offer something different from an advisor or consultant.
Joe Ball from PXN Group also encouraged founders to speak to someone they trust, but suggested they resist the urge to act immediately: “Wait a week, let that emotion settle, don’t rush into anything.”